
Blog / Insights
InsightsThe Fast Lane to ERC Funds with Buyout Programs
October 17, 2026 · 7 min read · By the SFG Capital team
How an ERC Buyout Quick Cash Solution Works
An ERC buyout quick cash solution allows businesses to sell their pending Employee Retention Credit to a commercial funder in exchange for an immediate discounted lump-sum wire payout, eliminating the months or years of waiting on government processing queues. Through this commercial transaction, you monetize an illiquid tax receivable into instant working capital while transferring the waiting timeline and administrative follow-up directly to the purchasing entity.
Waiting on the federal government to release your refund can severely disrupt payroll, growth initiatives, and everyday cash flow. The tax credit advance mechanism cuts through that gridlock entirely. When you opt for an upfront advance, you are not waiting on backlogged agency queues; you are executing a commercial asset sale.
In simple terms, a buyout provider purchases the beneficial rights to your pending credit. You receive an upfront, discounted cash sum right away, and when the Treasury finally issues the refund check, the funds go directly to the purchasing entity. If you want to dive deeper into the mechanics of these agreements, check out our resource on how to Sell Your ERC Claim: A Guide to Advance Payments and Buyouts.
The beauty of this transaction lies in the risk transfer. Most reputable buyout programs operate on a true non-recourse basis. That means once the deal closes and the wire hits your bank account, the buyer assumes the wait time and processing risks associated with agency processing backlogs. You are free to reinvest that capital into inventory, staff, debt reduction, or operational expansion without worrying about whether the government takes another six months or two years to cut the check.
Qualifying for ERC Buyout Quick Cash Options
Qualifying for an upfront payout requires clean bookkeeping and clear tax filings. Because the funder assumes the collection rights, they must verify that your claim meets every standard established under the Internal Revenue Service Employee Retention Credit program guidelines.
Key qualification requirements include:
- Filed Form 941-X: You must have properly submitted your adjusted quarterly federal tax returns for all applicable calendar quarters.
- Government Mandate or Revenue Reduction Proof: Clear documentation proving either full or partial operational suspension due to government orders, or qualifying gross receipts reductions meeting the statutory thresholds.
- W-2 Payroll Summaries: Detailed payroll records demonstrating qualified wage calculations and qualified healthcare expenses per employee.
- Clean Tax Standing: Ensuring there are no active federal tax liens, unresolved payroll tax liabilities, or undisclosed bankruptcies that might intercept incoming Treasury funds.
For business owners wondering if their filings meet current requirements, our guide on how to Don’t Wait for Uncle Sam and Use an ERC Buyout explains the eligibility criteria in complete detail.
Step-by-Step Guide to Securing an ERC Buyout Quick Cash Advance
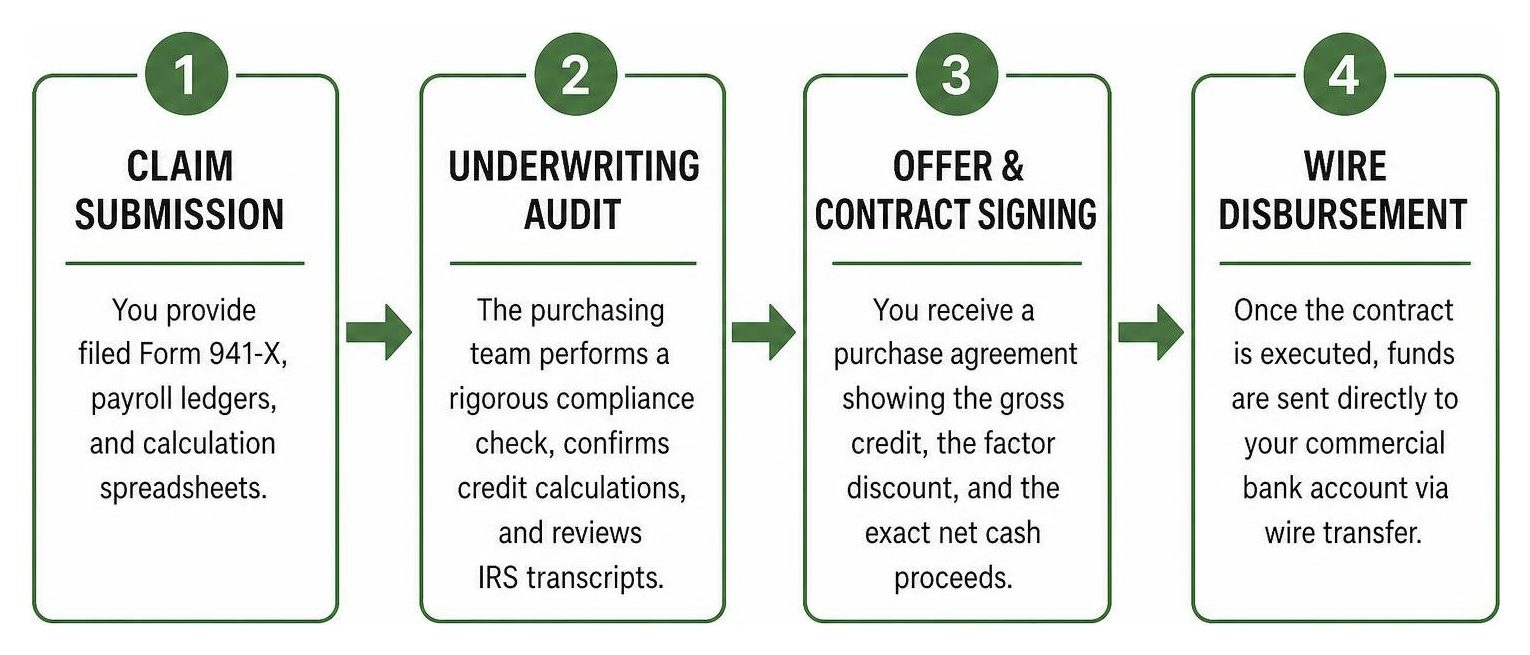
Getting funded does not require endless red tape. We have streamlined the process into a straightforward, predictable pathway:
- Claim Submission: You provide copies of your filed Form 941-X, supporting payroll ledgers, calculation spreadsheets, and organizational formation documents.
- Underwriting Audit: The purchasing team performs a rigorous compliance check to confirm eligibility, correct credit calculations, and review official IRS transcripts.
- Offer and Contract Signing: You receive a transparent purchase agreement showing the gross credit, the factor discount, and the exact net cash proceeds being wired.
- Wire Disbursement: Once the contract is executed, the funds are sent straight to your commercial bank account via wire transfer, delivering instant liquidity.
To put the speed advantage into perspective, take a look at how direct buyouts compare against standard government timelines:
| Feature | Standard IRS Processing | Commercial ERC Buyout |
|---|---|---|
| Average Timeline to Cash | 12 to 24+ months | 3 to 7 business days |
| Cash Flow Predictability | Highly unpredictable | Guaranteed upon closing |
| Underwriting Requirement | Government queue backlog | Rapid commercial audit |
| Payment Method | Paper check via mail | Direct commercial bank wire |
| Processing Risk | Borne entirely by business owner | Transferred to buyer |
Key Benefits of Selling Your ERC Claim

The primary reason business operators choose a buyout over waiting is capital efficiency. Having cash trapped on the government’s balance sheet prevents you from taking advantage of immediate commercial opportunities. If your business needs capital today, you can Bridge the Gap: Advance Your ERC Refund Today to eliminate cash crunches and maintain momentum.
The standout advantages include:
- Instant Balance Sheet Relief: You eliminate working capital bottlenecks by converting an illiquid tax asset into spendable operating funds without waiting indefinitely.
- Zero Ongoing Debt Service: Unlike a traditional commercial loan or merchant cash advance, a true buyout is a purchase of an asset, meaning there are no monthly principal or interest payments eating away at your operating cash flow.
- Shielding Against Regulatory Delays: As federal tax policies and processing guidelines evolve, holding an unliquidated claim exposes your business to extended moratoriums, audit pauses, and endless delays. A buyout locks in your value immediately.
- Capital Allocation Agility: Accelerating your refund allows you to seize volume discounts from suppliers, refinance high-interest debt, or hire key revenue-generating talent without hesitation.
Evaluating Total Costs and Buyout Discounts
Every buyout involves a factor fee or discount rate. This discount reflects the cost of capital, underwriting expenses, and the time value of money while the buyer waits out the government processing queues.
When evaluating your net proceeds, look closely at:
- The Factor Rate: Typically ranging between 10% and 30% depending on claim size, audit strength, and filing date.
- Fee Transparency: Ensure there are no hidden administrative fees, upfront legal retainers, or surprise filing charges subtracted at the closing table.
- Net Capital Delivered: Focus on the bottom-line cash amount wired directly to your commercial account versus the theoretical paper value of a check that might not arrive for years.
To learn more about calculating factor fees and maximizing your net payout, explore our detailed breakdown on an ERC Refund Advance.
Navigating State and Regional Buyout Programs
Regional economic conditions heavily influence how businesses manage capital. For businesses operating locally, having access to specialized regional programs makes a massive difference in transaction speed and local regulatory compliance.
Whether you run a tech firm in Austin, a manufacturing warehouse in Pflugerville, or a retail establishment anywhere in Travis County, local economic dynamics require partners who understand your operating environment. Local businesses face distinct commercial pressures, including rising commercial lease rates and competitive labor markets, making timely access to working capital essential. For comprehensive regional insights, read Everything You Need to Know About Texas ERC Refund Buyouts to see how local businesses are unlocking their tied-up claims and fueling continued regional growth.
Frequently Asked Questions About ERC Buyouts
How quickly can a business receive funds from a buyout?
Once all supporting documentation (including Form 941-X, payroll summaries, and tax transcripts) is submitted, the underwriting review generally takes 48 to 72 hours. Upon signing the purchase agreement, funds are disbursed via wire transfer, typically arriving within 3 to 5 business days directly into your verified commercial account.
Does an ERC buyout require repayment if the IRS delays?
No. In a standard non-recourse buyout agreement, the purchasing company assumes the risk of administrative delays. Because the transaction is a direct asset purchase rather than a loan, you do not make monthly payments, and you are not penalized if the Treasury takes longer than anticipated to issue the final refund check.
What documentation is required to finalize an ERC advance?
To finalize your advance, you will need to provide:
- Signed copies of all filed Forms 941-X for each qualifying quarter.
- Detailed payroll journals and calculation worksheets detailing qualified wages and healthcare expenses.
- Proof of eligibility (such as revenue reduction calculations or relevant government shutdown orders).
- IRS tax account transcripts verifying that your filings have been logged into the federal system.
How do buyout factor rates compare to commercial bank loans?
While commercial bank loans involve recurring monthly debt service, interest rate fluctuations, and restrictive covenants, an ERC buyout is an asset purchase. There is no ongoing monthly debt service, and the transaction does not add a liability to your balance sheet, giving you complete freedom over your capital.
Conclusion
Letting your hard-earned tax credits sit locked up in administrative backlogs only hurts your business growth. At SFG Capital, we partner with companies across Travis County, Austin, and nationwide to bypass processing bottlenecks, accelerate liquidity, and deliver fair, non-recourse advance solutions.
An ERC buyout quick cash strategy can be especially useful when your business has already done the work of filing amended payroll tax returns but still needs capital for payroll, vendor payments, hiring, expansion, or debt reduction. Instead of treating the credit as a distant receivable with an uncertain arrival date, a properly structured buyout allows you to evaluate a clear net payout, understand the discount, and make a practical decision based on today’s operating needs.
Ready to access your working capital without waiting on the government? Visit SFG Capital Services today to request a complimentary claim review and secure your upfront cash advance.
See what your business may qualify for.
60 seconds. No documents. No upfront cost.
General information only, not legal or tax advice. Eligibility and estimates are fact-specific and subject to review.