
Blog / Insights
InsightsAdvance ERC Payment Texas: Your Guide to Expert Advice
October 14, 2026 · 8 min read · By the SFG Capital team
Texas ERC Refund Help: Get Expert Review Before Funding
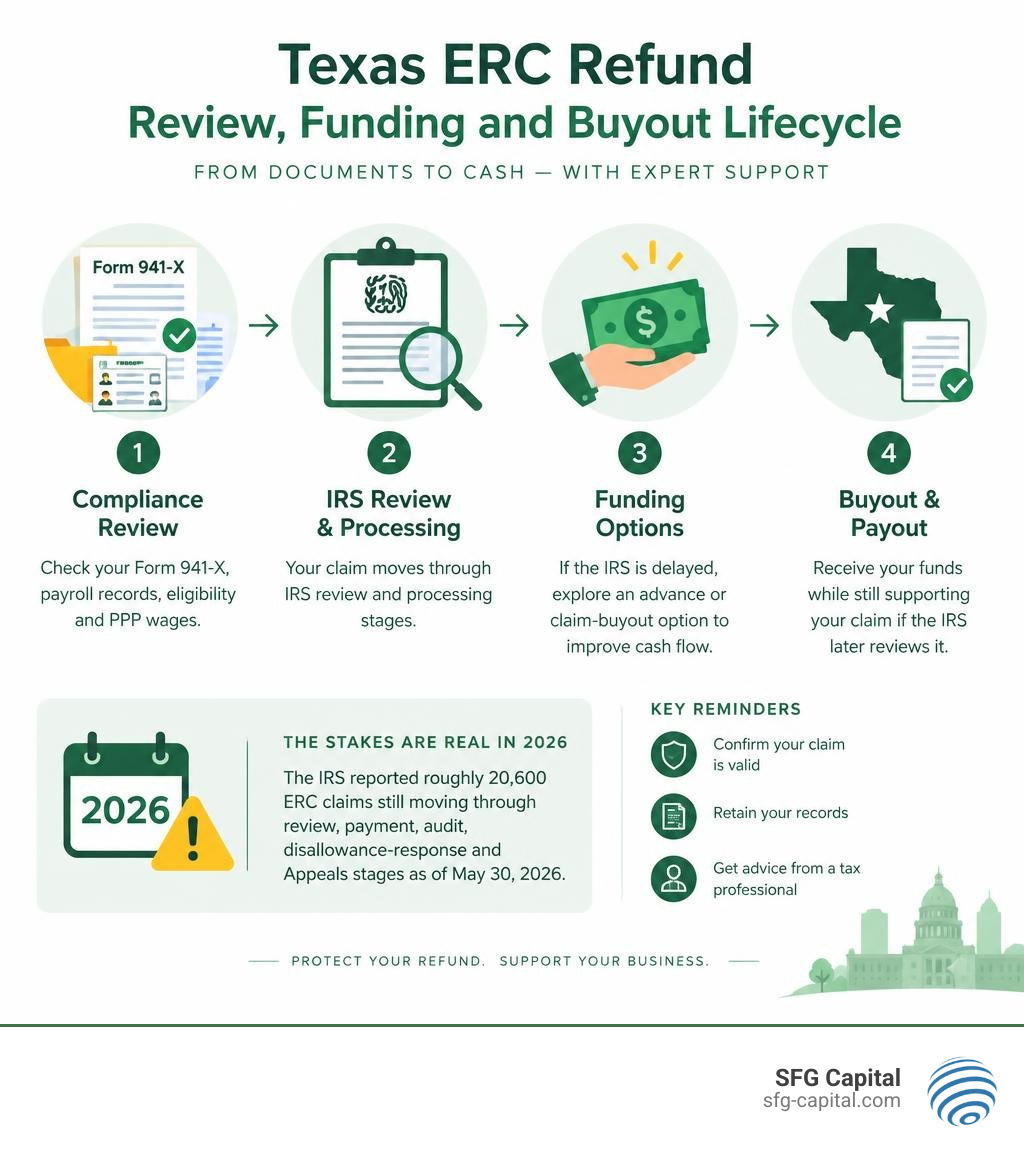
For Texas ERC refund help, start with a compliance review of your Form 941-X, payroll records, eligibility support, and any PPP forgiveness wages. If the claim is well documented but the IRS is delayed, a qualified ERC funding provider may evaluate an advance or claim-buyout option to improve cash flow without changing your duty to support the claim if the IRS later reviews it.
The stakes are real in 2026. The IRS reported roughly 20,600 ERC claims still moving through review, payment, audit, disallowance-response, and Appeals stages as of May 30, 2026. Before accepting funding or cashing an unexpected check, confirm the claim is valid, retain your records, and get advice from a tax professional who understands ERC audit risk.
I’m Santino Battaglieri, Founder of SFG Capital, with more than nine years of financial-services experience and extensive work funding and purchasing ERC claims. Our approach to Texas ERC refund help centers on careful documentation, disciplined underwriting, and working alongside qualified CPAs and legal counsel.
Texas erc refund help terms to know:
Current State of ERC Processing and IRS Enforcement in 2026
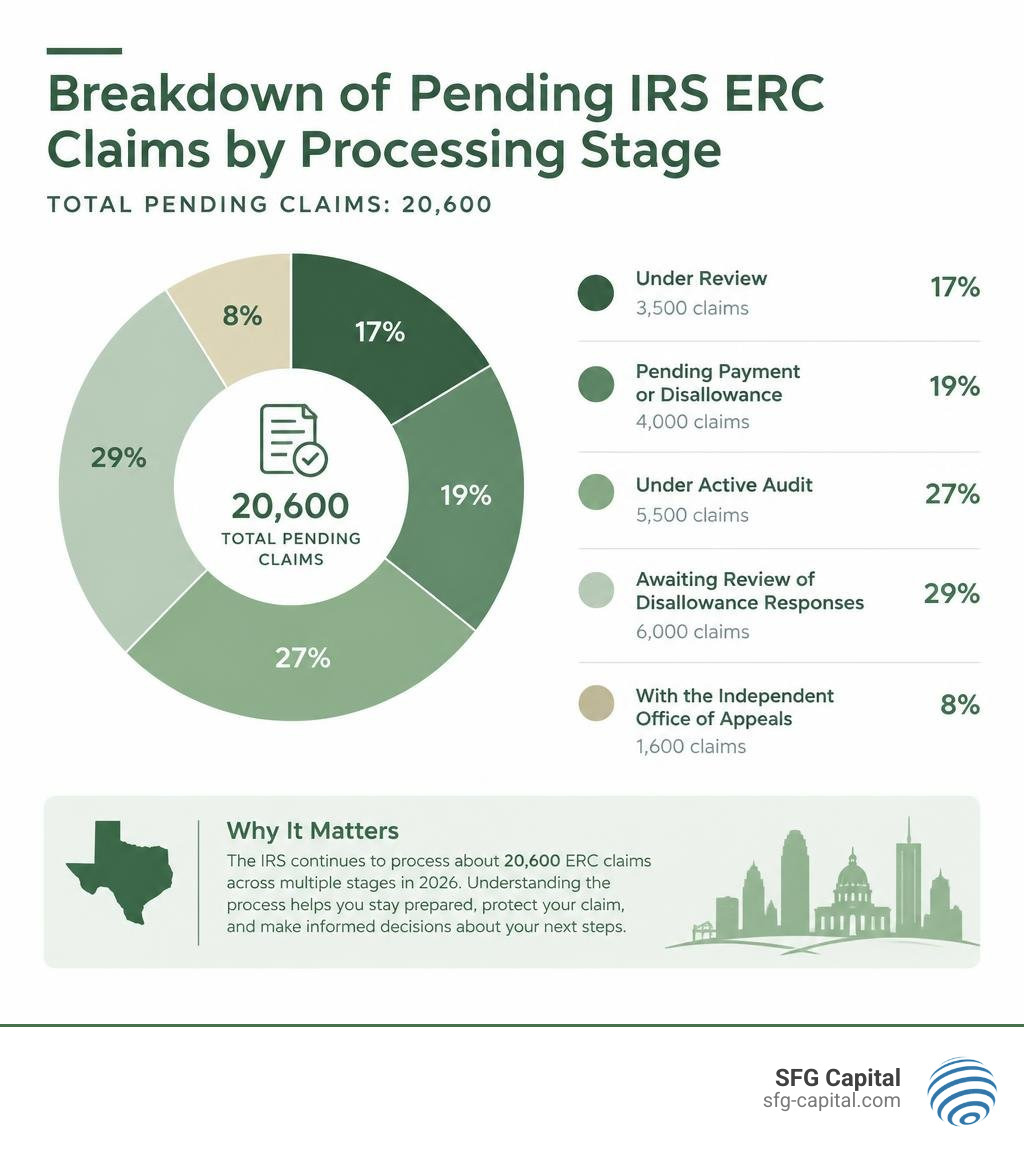
Navigating the Employee Retention Credit landscape in September 2026 requires understanding the aggressive scrutiny applied by the federal government. As of late spring 2026, the IRS continues to process a remaining inventory of approximately 20,600 ERC claims across several distinct operational stages:
- Under Review: 3,500 claims
- Pending Payment or Disallowance: 4,000 claims
- Under Active Audit: 5,500 claims
- Awaiting Review of Disallowance Responses: 6,000 claims
- With the Independent Office of Appeals: 1,600 claims
Backed by resources from the Inflation Reduction Act, the agency has trained approximately 400 dedicated agents specifically for ERC examinations. For business owners across Austin and the broader Lone Star State, staying informed about official Employee Retention Credit guidance is essential. Managing these delays strategically is detailed in our guide on The Texas Business Guide to ERC Refunds and Cash Flow.
Understanding Eligibility Criteria for Texas Employers
To withstand examination, every dollar claimed under the CARES Act and subsequent relief legislation must rest on substantiated payroll data and lawful qualification avenues:
- Gross Receipts Decline Test: For 2020, an employer had to experience a greater than 50% decline in gross receipts compared to the same calendar quarter in 2019. For 2021, the threshold dropped to a greater than 20% decline compared to either the corresponding 2019 quarter or the immediately preceding calendar quarter.
- Governmental Order Test: A trade or business subjected to full or partial suspension of operations due to direct governmental orders limiting commerce, travel, or group meetings due to COVID-19.
- Recovery Startup Business: Employers that began operations after February 15, 2020, with average annual gross receipts below $1 million, qualifying for up to $50,000 per quarter in Q3 and Q4 2021.
Credit calculations require precise accounting: 50% of up to $10,000 in qualified wages per employee in 2020 (maximum $5,000 per worker), and 70% of up to $10,000 in qualified wages per employee per quarter for eligible quarters in 2021 (maximum $7,000 per quarter per worker). Crucially, wages covered by forgiven Paycheck Protection Program (PPP) loans cannot be double-counted as qualified wages for the credit.
Handling Audits, Disallowances, and the Two-Year Litigation Deadline
If the IRS issues a formal notice of disallowance, the clock begins ticking immediately. Taxpayers face a strict two-year statute of limitations from the date of the disallowance notice to either resolve the matter administratively or file suit against the United States in federal district court.
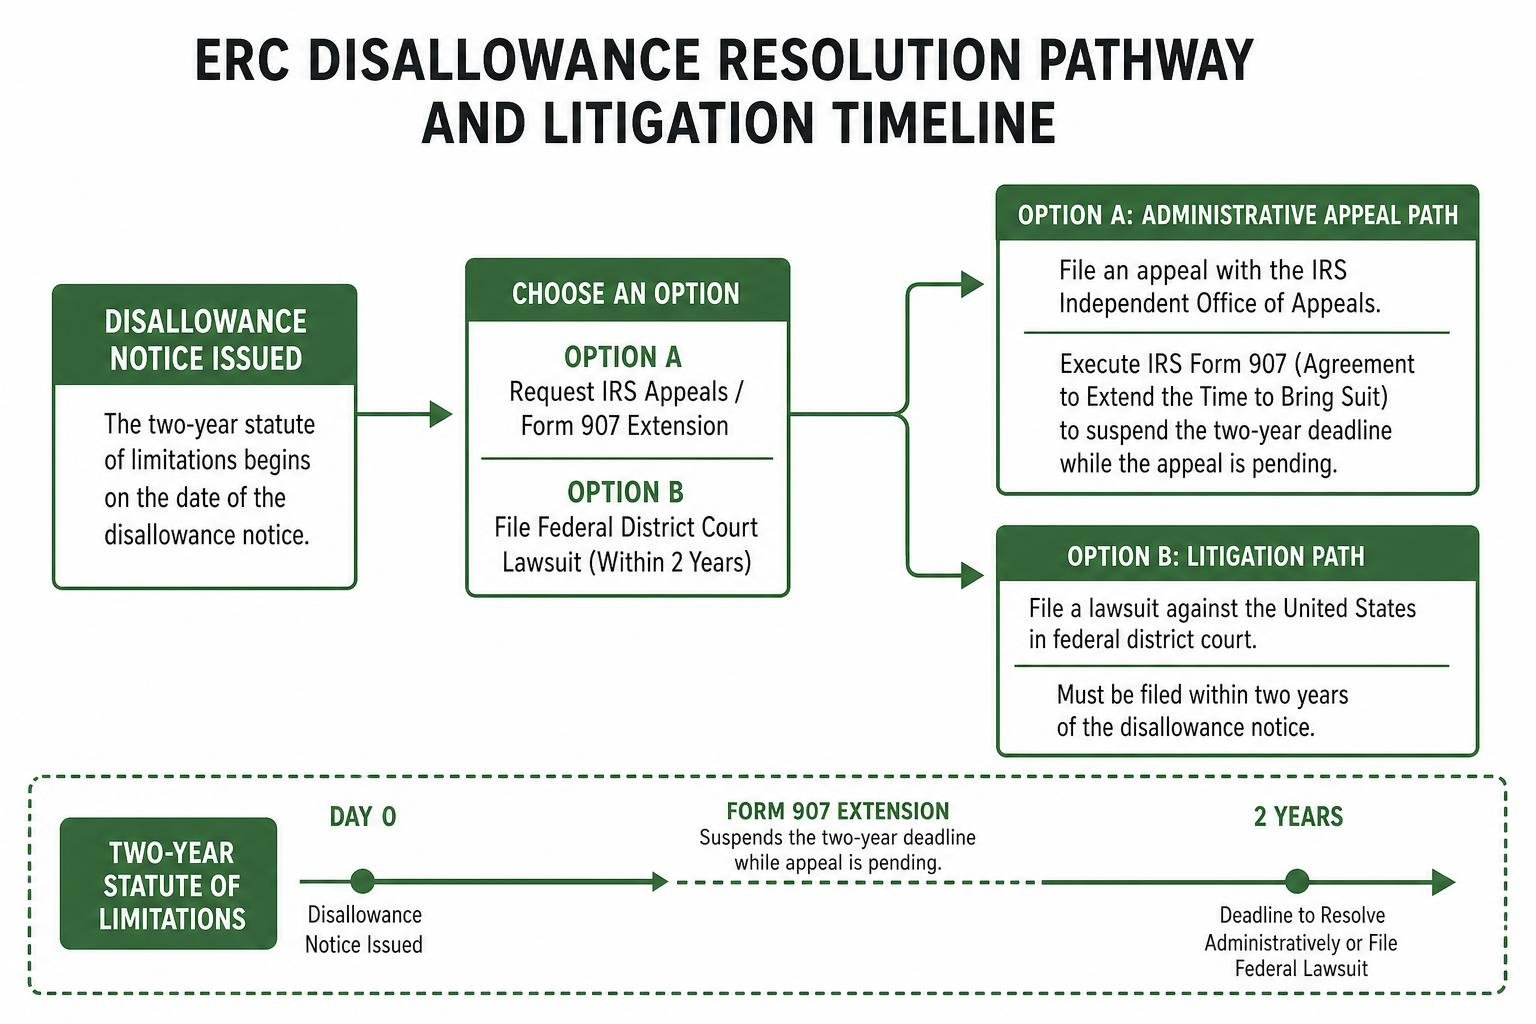
If an administrative appeal is pending within the IRS Independent Office of Appeals, taxpayers can execute an IRS Form 907 (Agreement to Extend the Time to Bring Suit) to suspend the two-year deadline. Proactively managing these notices protects your business from unnecessary clawback exposure, as outlined in our guide on how to handle IRS notices and audits.
How to Secure Reliable Texas ERC Refund Help and Avoid Promoter Scams
Aggressive third-party promoters promised easy windfalls, leaving thousands of business owners vulnerable to civil penalties and audit adjustments. Legitimate advisory services adhere strictly to Treasury Department Circular 230 standards, ensuring accurate legal substantiation before any forms are filed.
Warning signs of predatory promoters include:
- Guaranteeing six-figure refund amounts prior to reviewing detailed payroll journals.
- Charging contingency fees tied to inflated refund figures without providing ongoing audit representation.
- Relying exclusively on vague supply-chain disruptions without linking them to specific, mandatory governmental suspension orders.
Before committing to any third-party service, verify your filings and learn how to check your ERC status safely.
How Professional Texas ERC Refund Help Protects Against Audits
A defensible ERC position requires assembling a comprehensive audit defense file, including:
- Detailed, employee-by-employee payroll registers matching filed Forms 941.
- Direct mapping of local executive orders and municipal health directives in Texas impacting day-to-day operations.
- Clear wage reconciliation schedules isolating non-qualifying compensation, family members, and PPP-allocated payroll.
- Correctly drafted Form 941-X amended quarterly returns demonstrating transparent calculations.
Choosing the Right Texas ERC Refund Help for Advance Funding
Rather than remaining trapped in multi-year IRS backlogs, many companies leverage private liquidity options. Choosing the right financing structure allows leadership teams to deploy working capital immediately without waiting on federal processing cycles.
Underwriting for advance funding and non-recourse claim buyouts requires disciplined vetting. At SFG Capital, we review the underlying payroll metrics, government order citations, and IRS submission records to offer upfront capital. You can explore structured buyout mechanisms in our overview of Texas ERC refund buyouts.
Managing Received Checks, Claim Withdrawals, and Federal Tax Reporting
Receiving an unexpected check from the IRS requires careful verification before deposit. If an employer uncovers calculation errors or realizes a promoter submitted an illegitimate claim, the IRS provides specific administrative remediation programs.
For uncashed checks or unapproved pending filings:
- Mark the original adjusted return (Form 941-X) with “Withdrawn” in the left margin.
- Ensure an authorized corporate officer signs and dates the document.
- Submit the withdrawal package via the dedicated IRS withdrawal fax line at 855-738-7609, or mail it directly to the assigned audit examiner.
- If a physical refund check was delivered, write “Void” in the endorsement section and mail it alongside the withdrawal request to the Cincinnati Refund Inquiry Unit.
For businesses needing formal relief guidelines, the IRS ERC withdrawal procedure details exact step-by-step submission protocols.
Income Tax Treatment and Wage Deduction Adjustments
An ERC refund is not considered gross income under the Internal Revenue Code, but section 280C requires employers to reduce their deductible wage expenses by the exact amount of the credit claimed.
Recent IRS guidance provides welcome flexibility for reporting these adjustments:
- Year-of-Receipt Option: Taxpayers who did not amend prior returns can report the credit amount as income on their current corporate tax return (Form 1120 or 1120-S) in the tax year the cash refund is actually received.
- Disallowed Claims Adjustment: If a claimed credit was previously paired with a wage deduction reduction and the IRS subsequently disallows the ERC without dispute, the taxpayer may restore the deductible wage expense on their current-year return rather than reopening closed historical returns.
Texas State Tax Interactions and Comptroller Refund Overlaps
Because Texas imposes no individual or corporate personal income tax, the primary state tax touchpoint is the Texas Franchise Tax. Franchise tax calculations depend on Total Revenue, Cost of Goods Sold (COGS), or the Compensation Deduction.
When federal wage deductions are adjusted to reflect ERC compliance, Texas entities utilizing the Compensation Deduction must align their Texas Franchise Tax reports accordingly.
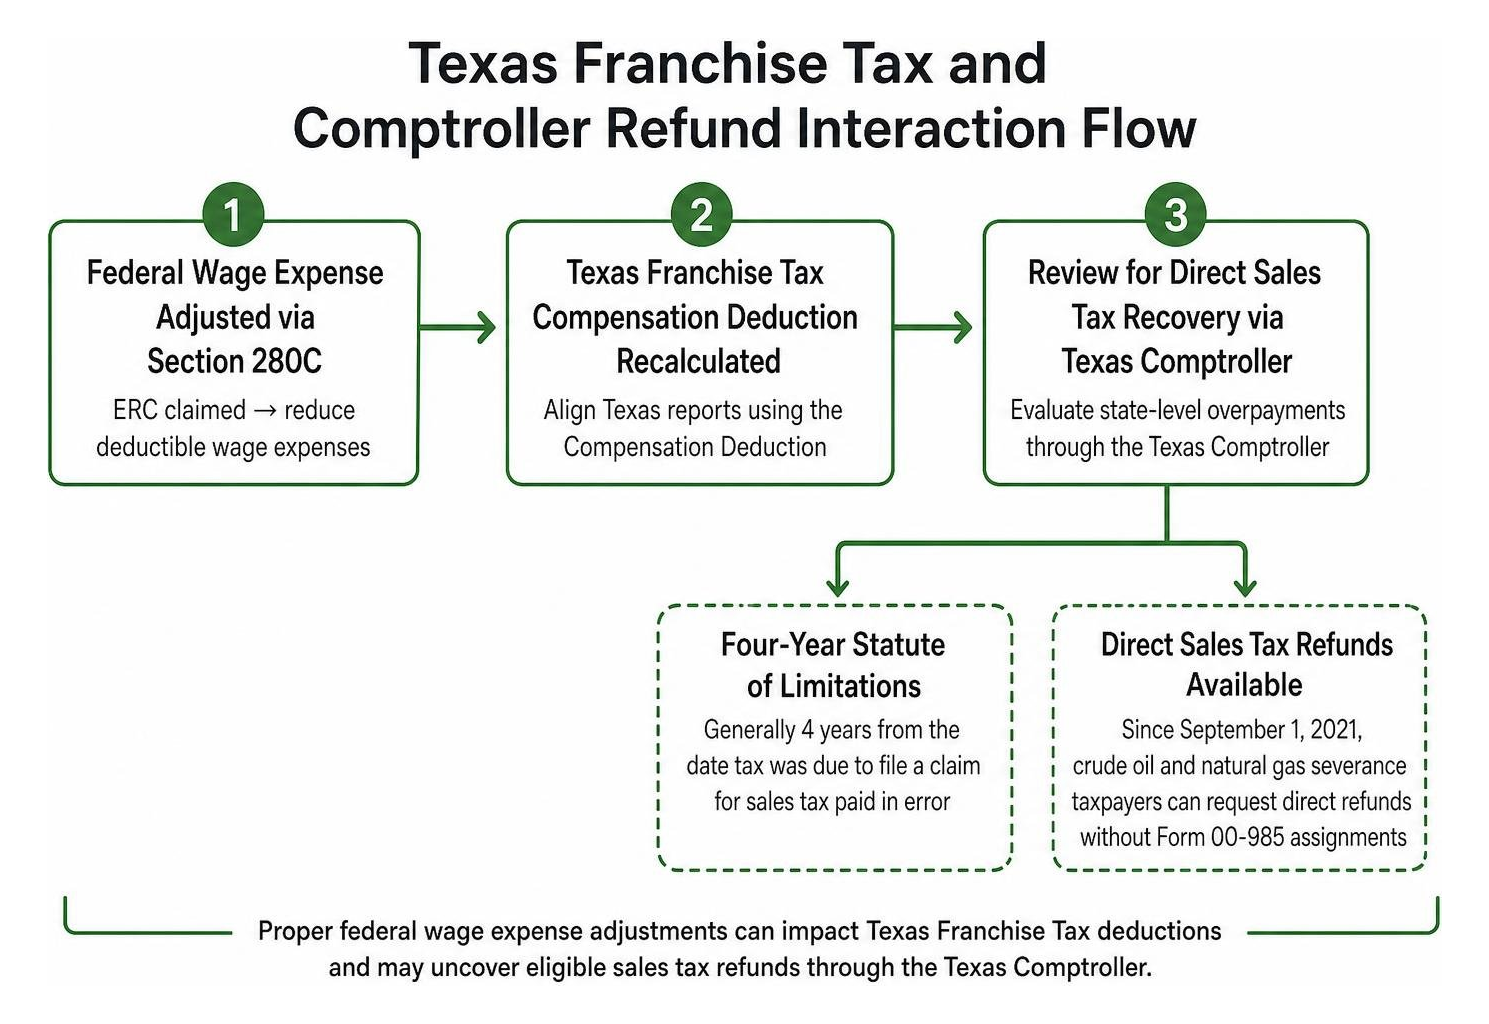
Additionally, businesses auditing their balance sheets can evaluate state-level overpayments through the Texas Comptroller. Texas law generally provides a four-year statute of limitations from the date tax was due to file a claim for sales tax paid in error. Notably, under rules effective September 1, 2021, crude oil and natural gas severance taxpayers can request Texas Comptroller direct sales tax refunds directly without needing Form 00-985 assignments from individual vendors. Broader details are accessible through the state’s sales tax refund guidelines.
Unlocking Immediate Capital with Texas ERC Advances and Buyouts
Waiting on IRS backlogs can stifle business expansion, hiring, and capital improvements. SFG Capital provides direct capital access to bypass processing bottlenecks safely.
| Feature | IRS Direct Payment | ERC Advance Funding | ERC Claim Buyout |
|---|---|---|---|
| Funding Timeline | Uncertain (Months to Years) | Days following underwriting | Days following underwriting |
| Repayment Source | Federal Treasury Check | Future IRS refund check | Future IRS refund check |
| Underwriting Focus | IRS processing capacity | Claim validity & documentation | Claim validity & documentation |
| Balance Sheet Impact | Asset receivable | Short-term liability advance | Clean receivable monetization |
| Audit Responsibility | Taxpayer maintains records | Taxpayer maintains records | Taxpayer maintains records |
Organizations seeking capital acceleration can review our dedicated ERC refund advance solutions or explore local financing options through our specialized ERC funding in Travis County services.
Frequently Asked Questions About Texas ERC Refunds
How long does the IRS take to process an ERC refund in 2026?
With roughly 20,600 complex filings remaining in the federal pipeline as of May 30, 2026, processing timelines vary widely. Straightforward claims clearing review may be paid within several months, whereas filings selected for audit or disallowance review can remain pending for extended periods.
Can I withdraw an ERC claim after receiving a refund check?
Yes, provided the refund check has not been deposited or cashed. The business must void the physical check, write “Withdrawn” across the amended return, and submit the entire package to the Cincinnati Refund Inquiry Unit to eliminate penalties and interest exposure.
What should Texas businesses do if their ERC claim is disallowed?
If a claim is disallowed, review the denial grounds with qualified counsel immediately. Taxpayers can file an administrative protest with the Independent Office of Appeals, execute Form 907 to extend their statutory deadlines, or file a refund suit in federal district court within two years of the initial notice.
Conclusion
Securing dependable ERC solutions empowers Texas business leaders to stabilize cash flow, protect against audit exposure, and reinvest in growth. Whether your organization is based in Travis County or operates across the state, SFG Capital provides the underwriting rigor and capital acceleration necessary to unlock your capital safely. Discover our full suite of funding mechanisms by exploring our comprehensive liquidity services today.
See what your business may qualify for.
60 seconds. No documents. No upfront cost.
General information only, not legal or tax advice. Eligibility and estimates are fact-specific and subject to review.